What would actually change if the UK had a government that understood modern monetary theory?
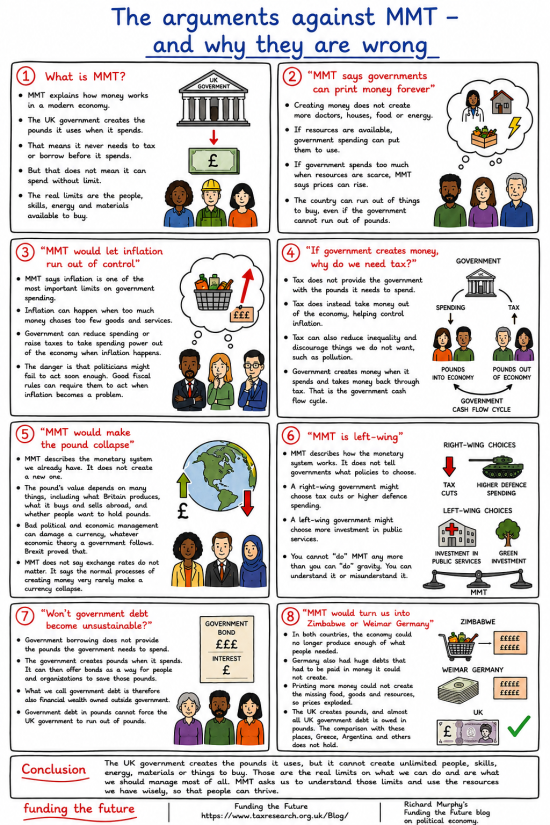
In one sense, very little: MMT describes how our monetary system already works.
But in another sense, I argue that it would change almost everything because government would understand the powers it already has.
In this video, I consider how an MMT-informed government might respond to another major financial crisis. Unlike the response to 2008, the objective would not simply be to restore the existing financial system and protect financial markets.
The fundamental difference would be one of control. I argue that an MMT government would recognise that a currency-issuing state can create the money required to respond to a crisis. Its real constraints would be resources, productive capacity, environmental limits and inflation.
I set out several immediate priorities. The Treasury would establish what emergency powers it could use, suspend its dependence on financial markets through the full funding rule, reconsider the payment of interest on commercial banks' central bank reserves and impose much tougher conditions on institutions requiring government support.
Banks requiring rescue would not simply receive another bailout. I argue that government support should come in return for ownership, with shareholders bearing the risks associated with their investments rather than expecting the public to protect their wealth.
The same principle should extend to shadow banking, including private equity and hedge funds. Financial institutions should not be able to escape effective regulation while expecting government intervention when their activities create systemic risks.
MMT would not eliminate the practical difficulties of a financial crisis. But it would fundamentally change who controls the response. Instead of asking what financial markets will permit, government could ask what action is necessary in the public interest.
The financial plumbing would remain largely the same. What would change is our understanding of it — and therefore who has the power when the next crisis arrives.
This is the audio version:
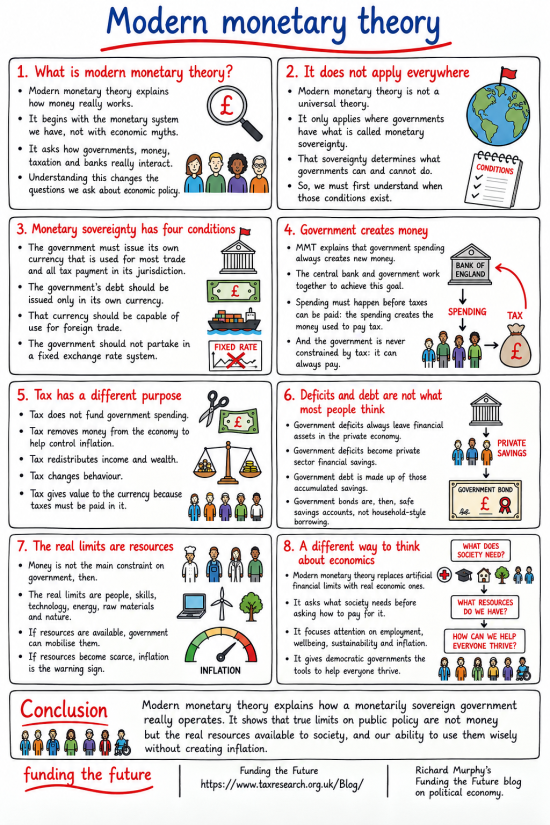
These infographics supports this video:
This is the transcript:
One of the questions I'm most often asked is: what would happen if we had a government that understood modern monetary theory, or MMT as it is commonly called? And I explain that in some ways it would make very little difference at all because MMT describes the way in which money already works within our economy. And in another way, it would change almost everything because we would have politicians who did understand how money works in our economy and the possibilities that that understanding creates.
Now, I need to give an example to explain that. I think, and I keep talking about the fact that I am expecting a coming financial crisis. And I lived through 2008, and I saw the crisis after the dot-com bubble burst, and I saw 1987. So I have been through these things before, and I want to use that example to explain what MMT thinking could provide in a situation where smart thinking would most definitely be required.
So what might a government that understood MMT do differently if that crisis occurred? That is the point of this video.
Now, let me stress again. MMT describes how money works in a country like the UK, which issues its own currency. The UK has its own central bank, an effective tax system and a currency that is traded internationally, and all its debts are denominated in sterling. That means it is a perfect modern monetary theory economy already.
Government spending creates money in this country right now, whilst taxation primarily exists to withdraw money from circulation that the government has previously spent into existence. And the purpose of that is to control inflation.
Government bonds provide savings opportunities rather than being a form of government spending. They literally never fund anything in the way that they are structured and used at present.
The real constraints on government action are the availability of resources, environmental limits, and the need to manage inflation.
A government that understood all these facts would have a different economic appreciation of the options available to it. That is the important point that I must communicate at the beginning of this video because it is that change created by understanding that is key to what an MMT government would deliver.
All the mechanics of the financial system could remain in place. We could have the same central bank. We would have the same currency. We would have the same taxation system if we desired, and we could still have government bonds. But our understanding of all of them would change, and the government would inevitably then use them differently. That is the point I am highlighting.
So, in the event of a crisis, a government that understood MMT would not need to introduce the new monetary system. It could keep everything the same, but it would, and I stress the point, yet again, manage the world differently.
Immediately, that government would understand that it would have to recognise that fiscal and monetary policy need to be coordinated rather than managed separately if the world is falling apart all around us.
It would have to focus on the availability of resources and the management of demand to control inflation, rather than on the management of financial flows, and that understanding would provide a basis for a different response to a financial crisis.
In 2008, the response was primarily to save neoliberalism. Oh yes, there was expenditure to support people indirectly when it came to unemployment and with regard to increased benefits in certain areas. VAT was reduced. There was a “Cash-for-Clunkers” scheme, which traded in old cars, in a supposed green move. But overall, most of the money that was spent by Gordon Brown, and subsequently by George Osborne for the Conservative-Liberal Democrat coalition government, was about saving the financial system from failure. That is vital to understand.
Over £400 billion was pumped into the economy at that stage for that reason. And I was told very directly, in a private conversation, I admit, by a senior official, then in the Treasury, that the government felt it had no choice but to do that. Neoliberalism had fallen off the wall as Humpty Dumpty had done, but they had no choice but to put him back on again because they said, that person said, there was no other alternative.
The point is, an MMT understanding of the economy would provide an alternative. We would not have to spend money to save our banking system in the way that Gordon Brown and George Osborne did, because alternatives would be available.
And if there is such a crisis tomorrow, and I was advising a Chancellor, because let me be clear, I do not ever want to be a Chancellor because I do not want to be an MP - what would I suggest they do? That is critical.
Immediately, I would suggest that the Chancellor establish several Treasury task forces, and the most important of these would be to work out what powers the Treasury actually has. Now, that's quite important, but at the moment it's unclear. Why is it unclear? That's because after COVID, the government introduced a whole range of emergency powers, most of which still remain in place, and most of which could be used by the government to overrule the operation of financial markets as they now are, so that changes could be introduced that could affect the way in which we manage the economy.
The point is, we would need to put in place systems that ensure that financial markets cannot determine the outcomes of another crisis, but that the government can. And so I would be telling a Chancellor, work out what you can do, and if you can't do it, work out how to create the powers to do so very quickly. You have to understand the monetary sovereignty that you've got and establish control over the crisis. That would be the job of the first task force that I would say should be created, and it will be required to start reporting within hours, and that would be vital.
I stress, being in charge, is vital. The difference between a neoliberal government and an MMT government is that an MMT government has the mindset that says it is in charge and not that markets are. That is a fundamental change of view. I cannot stress the importance enough.
The second priority would be to begin to create changes. So I would, for example, create a task force to look at the suspension, the immediate suspension, I must say, of the full funding rule, which requires that the government balance its financial books every day by issuing Treasury bills and government bonds to match any shortfall in tax receipts that have arisen during its course.
This full funding rule was introduced by Sir Geoffrey Howe, the Chancellor of the Exchequer under Margaret Thatcher in 1981. There was no reason for this rule. It was a political choice, and it was designed to create government dependence upon financial markets. It would've been entirely possible for the government at that point in time to have continued to borrow directly from the Bank of England as it had done for a very long time, and which it did to some degree do until 2006, because there was a continued operation of what was called the Ways and Means account, which was effectively a government overdraft, until that time. But we now have total dependence upon this rule, and it would have to go.
Is it possible for it to go? I know it is. How do I know that? Because in March 2020, when the COVID crisis was developing, the Bank of England offered the government a £20 billion overdraft facility for the duration of the crisis. That was terribly generous of them, given that the government owns the Bank of England. But the point was, the facility existed. The capacity to create money by direct loan to the government was there. There is no requirement for the UK government to have to go to markets to find money. A government that understood MMT would realise this. It would realise that money was under its control and markets were secondary.
That is a major difference of view. And I emphasise the consequence would be a fundamental change in financial power in the UK. An MMT government would make clear that issuing government bonds was not necessary to finance its spending. The City of London could not therefore dictate interest rates during the course of a crisis. It would not rely upon the collection of tax as the way of funding government activity because that is not what actually happens. It would instead create the money to keep our economy going. It would change taxes to ensure it could manage the inflationary consequences. That would inform its taxation policy.
All of this integrated thinking would mean that a government that understood MMT could have a coordinated plan in operation to manage the financial consequences of a crisis almost immediately. A government, a neoliberal government, could not, because it does not believe it's in charge, and that is the difference.
The third priority that I would address would be to tackle how our commercial banks receive interest from the government. Commercial banks maintain what are called central bank reserve accounts at the Bank of England. Now, those balances grew from £20 billion in 2007 to more than £900 billion by 2021. The money that inflated those bank balances did not come from the banks themselves. It was created by the government and injected into the economy through the quantitative easing process.
Let's not go into the details of the mechanics at this moment. The point was, the banks had their deposits with the Bank of England inflated as a consequence of deliberate government action. And then quite absurdly, the UK government insisted it had to pay interest to these banks on the deposits that they held with it, even though the commercial banks in question had not created that money.
I would now withdraw payment of interest on some of those balances. How much? Well, there's around £600 billion of those reserves left. I would at least halve the balances at the first instance that would have interest paid on them, and any new reserve balances that were created as a consequence of the government borrowing directly from the Bank of England and then spending money into the economy would not carry interest. We cannot go into a crisis knowing that the government has not only to pay the cost of the crisis, but also pay the banks for the privilege of providing them with funding as a consequence of the crisis. That would have to stop, but only an MMT government would understand that.
And the next priority and the next issue that a task force would have to look at would be how to rescue banks. We are going to get bank failures again in this country. We are going to get secondary banking failures. The government will have to decide how to provide emergency support, and it will have to put conditions on that support, and this time there won't be bailouts. There will only be takeovers. The government will buy shares in the banks that require support at this time, and they will do so at the value of the banks at the moment they require support, not at the value they had before the support was required.
In other words, old valuations set by stock markets will be almost irrelevant. If the bank is under financial stress because it has no money at a moment, it is effectively bankrupt, and the valuation that will be paid for the new shares to be issued to the government to bail it out will be valued on that basis. And any bank that tries to get around these rules by using the arrangements of the sort that Barclays used in 2009 would not be allowed to do so.
An MMT government would not be held to ransom by banks demanding unfair payment for support that they absolutely, essentially require.
We would need to support banks, but we would not support their shareholders. Those shareholders will have known the risk that they're taking. They will have been able to foresee, as I have, that there would be a financial crisis coming. If they decided to maintain their shareholdings, so be it. They will pay the price.
We will not have this crisis being used to support wealth as it was in 2008. This time, the focus of an MMT-understanding government will be upon reducing financial risks that would have to be assumed by the public. And one way to do that is to reduce the cost of the support that will be supplied to shareholders. That is critical.
And I could keep going on. For example, a fifth priority would be to control the shadow banking sector. This is a detailed and complicated issue, but effectively, this would require that hedge funds and private equity be brought within the scope of banking regulation, and all the issues that I've so far talked about would be applied to them. And if they require bailouts, they too could be subject to takeover by the government. Their assets would be taken in exchange for the financial support they needed.
The objective would be to ensure that financial institutions could not escape effective regulation by operating outside conventional banking. And the secondary objective would be to ensure that those with wealth do not maintain their privilege at cost to society at large during the course of a crisis.
So how would this response differ from what happened in 2008?
An MMT government would understand that it could create the money needed to intervene in a crisis. It would not need the pretence of QE and the subsequent quantitative tightening. It would simply borrow from the Bank of England and say, “That's what we're doing.” It would be open and honest. It would therefore not regard financial and market approval as a prerequisite for taking action. And the Treasury and the Bank of England would be required to coordinate their policies to manage the crisis.
Financial institutions requiring support would have to accept government-imposed conditions reflecting the public interest. Shareholders would be decidedly secondary, and the government would not assume that restoring the previous financial arrangement was its overriding objective of a bailout. It could instead use its monetary powers to establish a different relationship between the state and financial markets.
An MMT government would therefore be in charge, saying which, it would face practical constraints.
Understanding MMT would not mean that the government could achieve everything it wanted. Managing failed banks and financial institutions would require experienced people. The government would have to hire them. That would be necessary. But that is one of the understandings that the government would create. It wouldn't outsource the responsibility for managing a failed financial system to members of that failed financial system. It would hire people into the government to undertake that activity on behalf of the public.
This will be a total change of attitude. It will be fundamental to achieving the outcome that I think will be necessary as a result of this crash, and that is key. The whole issue is about who controls the response to a crisis. MMT puts the government in charge. Neoliberal thinking puts the markets in charge.
The fundamental difference that we would see if we had an MMT government would be that the response to a crisis would be determined in the public interest rather than for the benefit of the financial institutions whose failure had created it, and that matters. And that is the sort of difference that having a government with MMT understanding could create.
I will make other videos of this sort, but understand MMT changes everything whilst keeping the financial architecture in place. The plumbing doesn't alter. The way in which we understand it changes fundamentally. The consequence is we will get better government, better democracy, and an advance of management in the public interest, and that to me is what matters.
That's what I think. What do you think? There is a poll down below, of course. Please let us have your comments. Please do like and share this video. Please do subscribe to the channel. Please do click that bell button. And if you'd like to support our work, because we are heading for a crisis and we will need to continue to work through it, there is a coffee or Ko-fi button down below that you can use to support our work, and we would be very grateful.
Poll
Thanks for reading this post.
You can share this post on social media of your choice by clicking these icons:
There are links to this blog's glossary in the above post that explain technical terms used in it. Follow them for more explanations.
You can subscribe to this blog's daily email here.
And if you would like to support this blog you can, here:
-
Richard Murphy
-
Support This Site
If you like what I do please support me on Ko-fi using credit or debit card or PayPal
-

-
Follow me
 Buy me a coffee!

I would like any bailout of the private banking system to be a loan to those banks – plus interest.
In other words, I’d want the bailout paid back. The money the U.S. Fed paid out in 2008 for example seemed to be a one way pay out. The bail outs over here – was that money ever paid back?
And yet we are told bond holders hold our government’s debt and ex-Goldman Sachs politicians add interest to the CBRA to make it look like a debt against the currency issuer. Again, if any central bank bails out a private banking system, the principle is that they must pay it back – and the rest (more intervention in what they do).
It seems to me that all that happens anyway is that the bailout creates the excuse to do more austerity as though everyone has benefited from slack regulation when they have not (socialize the losses). My view is that the crisis should be contained within the system that caused it as much as possible – nationalization if necessary. Then – maybe – the City might learn a bit more about ‘risk’. Any crisis like that needs to be used to get more control – not pay them to keep being stupid.
‘Saw the first 15 minutes of Stephanie Kelton’s YouTube film last night. The bloke wheeled out by Biden as a ‘key economic thinker’ and who could not explain MMT is priceless to watch. I’ll finish it this evening. But to see such ignorance in action was a mixture appalling and grim satisfaction that our suspicions have been realised: the world is ran by totally out of touch and badly educated people in key positions.
Answer: Keep keeping on.
I will. So will you, I hope.
I’m not sure why the government would wish to lend money to a failed bank? Surely the government would simply take it over, at it’s current value, i.e. zero, for a nominal £1, with shareholders and unsecured bond holders wiped out? The bank would continue to run, with finance provided by the government and, in time, it may become viable again. At that time the government could sell it back to new shareholders. I see little point in the government owning a commercial bank long term, though I would like to see the Bank of England offer retail accounts.
Am I missing something?
Yes, shareholders (and subordinated debt holders) should be wiped out entirely. In 2008, the (implied) threat of letting the system collapse into chaos meant that shareholders got something (not a lot, but something)… but more importantly (at least to the general public), executives walked off with pensions, prior bonuses etc. in tact. This must not happen again…. and we (hopefully) learnt from 2008 to make sure this doesn’t happen.
Senior unsecured bond holders are tricky. Yes, they rank behind depositors (in a liquidation) but if the bank is not liquidated (where bond holders get any cash remaining after depositors are paid out) and they are arbitrarily wiped out these bond holders will have a serious claim against government in the (very likely) event that the bail out restores stability. Indeed, Government made a small profit from the bail out in 2008 (despite poorly managing their holdings) so bond holders would have a serious case.
Of course, one can argue that without the bailout their bonds would be worthless but again, after a bailout we would never know the “counterfactual”. (Interestingly, we get a similar dynamic with negotiations over water nationalisation)
In the end, I think senior bond holders should take a hair cut but it needs to be modest. Realistically, interest rates would be cut sharply and that will lead bond prices to rise… so, if bond holders effectively get guaranteed after a bailout they would make windfall profits. Perhaps they could be exchanged into a gilt at the prevailing (low) gilt yield?
Thanks, Clive.
All I’m thinking about here Tim is the collateral damage on the rest of the banking system should a bank fail – who gets hurt? I have very little faith in the (lack of) compartmentalization of the finance system (derivatives etc) as it far too easy for banks to do what they want and break rules in search of profits. Under Reeves, I understood that some protections from 2008 were loosened for example. It might in the system’s interest to keep a failed bank going at least until its full position is known. The high street and commercial banking sectors should be kept apart – but have they? It takes having a lot of faith in the FCA that I do not have.
There is no chance of a bank failure without a domino effect.
I know capital bases have been improved, but the scale of interaction is too great for anything else to happen, especially in the situation of confusion that would exist in that environment.
PSR
I mentioned that Biden advisor here the other day. I was amazed that he was so confused. It is one thing to have firm view that is wrong. Another to faff about like he did.
It depends how typical he is. I am trying to work out if people like that are easier to convince about a new MMT paradigm or more difficult.
You are correct, a (major) bank failure would have a domino effect – not like 2008 because of increased capital and radically reduced unsecured interbank lending – but the broader universe of financial market participants would run for safety and seize up the system.
How likely is a major bank failure?
I took a random UK clearing bank. It had “loans and advances to customers” of £480bn and tier 1 equity capital of about £41bn and other loss absorbing capital (sub debt etc.) of £6bn… or 10% of the loan book. This may not sound much but imagine all this is mortgage debt and we have a 40% fall in house prices and and 20% of people default on mortgages (with an 80% LTV) then the loss to the bank would 8% of capital – still not enough to wipe out all the capital.
I would also note that if, in a failure, senior bond holders were forced to take a hit then it would have a serious consequence for pensions where liability matching with bonds (including bank bonds) would make then vulnerable.
Are yousaying they would not fail, then? What about liquidity? The denial of that is what would kill banks.
Liquidity regulations have changed the landscape hugely. Banks no longer fund their activities in the interbank lending market and can, under certain assumptions, survive for 30 days without access to borrowing. That gives quite a lot of time to sort out liquidity issues (which was totally lacking in 2008 with RBS).
The questions for me are 1) are the assumptions about the “stickiness” of deposits correct in a modern internet banking world? SVB failure suggests not. 2) What will happen to other institutions – insurers, pension funds, shadow banking etc..
Here – we just don’t know.
A banking crisis is always a risk but it is far smaller than 2008. The same cannot be said for other sectors.
I think the crisis will be in the secondary market and spillover.
Just one caveat regarding the poll. Understanding MMT alone would be insufficient. There would also need to be a motivation to apply that understanding in the service of the politics of care, as opposed to in the service of other ends (fascism, for example). I would hope that the majority of our MPs would not be cynical and diabolical enough for this distinction to matter and any that were would be held to account by the public. This, for me, makes it extremely important for the public to also understand the policy options inherent in MMT, not just the government.
I hoped I had made that clear.
I will keep reiterating it.
Yes, you do make it clear in all your writing. It was just the specific wording of the poll.
Thanks again for another crucial “root of a problem” article.
Might it be that a governmental avoidance of M. M. T. analysis and use is a consequence of our society’s governance being undemoctratic?
Might the reality of our governance be that we are governed through a subverted form of polyarchy in which the financial sector dominates the other groups which comprise our society?
P. S.
1) Financial institutions that employ former U K Chancellors see an average 59% increase in official meetings with government.
2) Over the last 40 years, every single former Chancellor has transitionally accepted a paid position in the financial sector after leaving office.
3) The combined finance lobbying structure boasts a combined annual lobbying capacity of over £145 million
(From AI Overview)
This is purely a personal observation but it seems to me that the term “neoliberalism” is now finding wider recognition amongst the general public. Not long ago, if you used the term most people stared at you blankly. Now many people I meet have some understanding that it means something and that it might just be the reason why life is so hard. It may be small progress but it is progress all the same. I hope PSR can get round to finishing Stephanie Kelton’s film because it was well worth it – and yes the discomfort of Jared Bernstein was a joy to watch. And to think these people are still in charge of the global economy beggars belief!?
There is a video coming on this at the weekend.
Finding the Money?
https://www.youtube.com/watch?v=x3TJFoQWCHA
I’ll have to take a look at it. Stephanie Kelton is Bernie Sander’s economic advisor.
I am not sure about “is”, but “was” is correct.
Great post, thanks, one of your best of recent years.
I have a technical question: why still pay interest on any of the banks’ central bank reserves? Are the banks cashflow-dependent on that revenue stream, and would the intention be to taper this over time?
I also propose a thought experiment: what do we think would happen if you convinced the Chancellor and PM to do this? It implies a genuine movement of power from corporate to democratic, and those with power currently will not like this one bit! Ruling party politicians, whether corporate-owned or true believers in the household analogy, and their followers, would likely be organised to stage a coup, initially at least by a leadership challenge through the current political conventions. So, how is this to be prevented, considering that those currently with power ‘hold the microphones’ and therefore control the narrative?
Thank you. Those are two important questions.
On the first, interest is paid on central bank reserve balances because this is one of the mechanisms through which the Bank of England seeks to influence interest rates throughout the economy, including longer-term rates. The payment is not pointless. It has a genuine monetary policy function.
But there is considerable doubt as to whether interest needs to be paid on every pound of reserves to achieve that objective.
The banks cannot collectively get rid of these reserves because they were created by the Bank of England. That raises the question of why the Bank should pay interest on all of them when paying interest on only a proportion might be sufficient to achieve its policy objectives.
I would therefore favour a carefully managed transition towards a tiered system, in which some reserves receive no interest whilst others continue to be remunerated. This could save the government substantial sums without, I suspect, sacrificing effective control over interest rates. The transition would need to be tested and managed carefully, rather than imposed overnight.
Your second question concerns political power.
I agree that such changes would face opposition from those who benefit from existing arrangements, including parts of the financial sector and those who defend the current economic system.
But I would not assume that a leadership challenge or political coup was inevitable.
The answer is to explain the changes, demonstrate their benefits, build public understanding and establish sufficient political support before implementing them.
That is why changing the public understanding of money and banking matters so much. Economic reform cannot be separated from the political work needed to make it possible.
Without that preparation, even sensible reforms can be defeated by those who benefit from the status quo.
I can only repeat a point I made a few days ago. With such a huge majority of MPs who would not want to see another leadership spill so soon, Andy Burnham has the opportunity to push through radical changes that many of his own side may not support in private and then ride out the inevitable backlash without being dumped. That opportunity has probably passed already, even if he were to wake up tomorrow screaming ‘Get me Richard Murphy’s phone number! NOW!’
No call, yet.
There’s no need for a coup or revolution. We just need to demonstrate that good returns can be achieved by investing private capital in social programmes, in partnership with the public sector. It’s not a fantasy. It can be done.
This is an excellent outline of MMT in crisis response but for me its real power lies in long-term policy influence.
We need n nurses, teachers, carers, engineers, construction workers, bus drivers et al in x years time? Fine, let’s invest now, start training now. Worry about planning and resource not funding.
Richard, you touch on “It would hire people into the government to undertake that activity on behalf of the public.”…. I suspect that there is an enormous cohort out there that would gladly identify as patriotic in the truest sense and work for the good of society as a whole.
Thank you, and I agree with you.
I totally agree with PSR about Stephanie Kelton’s film, Biden’s adviser was embarrassing. It was heartening, however, to see how many experts backed her up throughout the film . Then you realize how effective the mainstream cover up is. I guess everyone has to keep banging on about it. Beat them into submission.
That’s it.
If the government said they were going to abandon the full funding rule the value of sterling would plummit as the forex market would dump pounds due to impending inflarion.
Why?
Your comment is unreasoned.
But if you want to be unreasoned, would it be worse than Brexit? Why?