What is money? We use it every day, but most of what we are taught about money misrepresents what it actually is. In this Understanding Economics video, I explain why money is not a physical thing at all.
Banknotes, coins and the numbers in your bank account are representations of something else, which are promises to pay. Money records debts between people, banks and governments. What you think of as money in your bank account is, in accounting terms, just a promise made to you by your bank.
This is not a new idea. From tally sticks and coins to banknotes and modern electronic payments, money has always depended upon records of obligations. When payments take place today, nothing physical has to move between bank accounts. Accounting records simply change to show who owes what to whom.
Banks also create new money when they lend. When a bank provides a loan, it simultaneously records the borrower's debt and creates a deposit that can be spent. When that loan is repaid, those records are cancelled, and that means that the money the loan created then disappears.
Government money works through a similar process. Government spending creates money, while taxation removes it. The requirement to settle taxes in pounds also creates continuing demand for sterling throughout the UK economy.
But, in all this, money should never be confused with real wealth. Money cannot build houses, grow food, teach children or care for people. Those things require people, skills, knowledge and physical resources.
Money is an extraordinarily important economic tool, but it is ultimately a system for recording promises and organising economic activity. Understanding that distinction between money and real wealth is fundamental to understanding how our economy actually works.
This is the audio version:
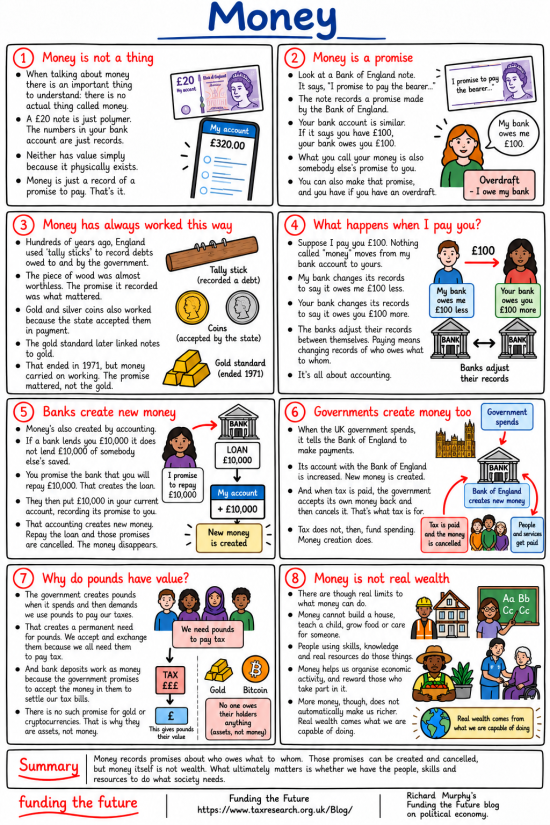
This infographic supports this video:
This is the transcript:
Hello, I'm Richard Murphy, and this is Understanding Economics, the series of videos that I am making, which explains economics in the way that I see it. And I stress this is about economics in the way that I see it because I do not see economics in the same way as every economist does, and that is because I think that most economics has failed us. And so I am looking for a different explanation of the economy in which we all live that looks at the actual facts that we can observe in our society and explains them in a way that makes sense to me, and I hope makes sense to you.
This, then, is a series about re-understanding economics, and in this video I want to look at something which is about the hardest topic in economics to explain, and that is money.
Money is really difficult to understand, and that's because most of the things that you have ever been told about it and most of the things that you understand about it are probably wrong. I'm sorry to have to say that, but that's a fact.
The most important thing of all to understand about money is that there is no such thing as money, and by ‘thing', I mean a physical substance.
A £20 note is just a piece of polymer. A physical paper note in another country is just a record of a debt owed to a person by the government that printed it.
Coins have the same effect.
And even the numbers in your bank accounts are just records. They are not a note of the physical existence of anything. There is no such physical thing as money. What we can see, which we think represents money, is no more than a representation. It is not the money itself because money is just a record of a promise to pay, and that is it.
And if you want evidence of this, look at a note printed by the Bank of England. It says on it, ‘I promise to pay the bearer…' the sum of whatever the value of the note is. That's what tells us that this is a promise and it records a debt. You haven't been paid this money by the Bank of England. They promised to pay that money to you, and that is something quite distinctly different. And therefore the note is not money. The note records a promise to pay money.
And your bank account is similar. If it says you have £100 in your bank, your bank owes you £100. What you call your money is actually somebody else's promise to you.
And let's be clear, you can also make that promise and, in effect, create money, and you do so if you have an overdraft. You have promised to repay your bank the £100, or whatever it might be, that is in your overdraft.
Promises are what make money, and that's always been the case. Money has always worked in this way. Hundreds of years ago, England used tally sticks to record debts owed to and by the government. These were pieces of wood which had notches marked on them, and they were split down the middle. This recorded a debt, and when the debt was repaid, the tally stick was burned. The slate was wiped clean. But until it was repaid, the half of the tally that remained with the person who owned the debt could be sold as if it was money. The half that recorded the liability recorded the fact that somebody had made a promise to pay and they had to do so.
And gold and silver coins also worked in the very same way. They recorded the fact that the state would accept them in payment for taxes. They recorded the debt that the government had created by spending money into the economy and the fact that it could be cleared by making payment back to the state by way of tax using the coins it had created.
And the gold standard later linked notes to gold, and that created money that we thought was backed by a physical product. It wasn't. It was actually still backed by the government's promise, and that promise was that it would accept the note to a specific value in payment of taxes. That ended in 1971 when the US came off the gold standard.
At that point, gold ceased to have any meaning inside the world's monetary systems. But although gold ceased to have value, money carried on working. In fact, a dollar note that was issued before the time that the gold standard was abandoned worked just as well after it was abandoned. What mattered was the promise, not the gold, and what stood behind the promise was the government. The physical representation of money has never been anything more than a record of debt. That's all money has ever been.
So what happens when you make a payment? Suppose I pay you £100. Nothing called money moves from my bank account to your bank account. My bank changes its records to say it owes me £100 less than it did before the transaction took place. Your bank changes its records to say it owes you £100 more. The banks adjust their records between themselves through the Bank of England, if necessary, to record the fact that this has taken place. But payment means changing records of who owes what to whom.
Money is all about accounting. The two are inextricably linked. Double entry bookkeeping is fundamental to the way in which money works. It is the way in which we record the existence of money, and it always has been, even before we recognised that double entry bookkeeping existed, because money is always a promise to pay. Somebody, one side of the entry, has promised to pay somebody else, the other side of the entry, and that's what the accounting records.
And money's also created by accounting, and this is incredibly important to understand. If a bank lends you £10,000, it does not lend £10,000 of somebody else's money that's been saved with the bank. In fact, it can't do that because it's promised to repay the £10,000 in question back to the person who deposited it with the bank. You instead promise that you will repay £10,000 to that bank, and that's what creates the loan. Because you've promised to pay £10,000, they promise to let you spend £10,000, and they record that by putting that money in your current account, and you could then go off and buy whatever it is you want, a car, a kitchen, whatever.
That accounting creates new money. Repay the loan in that case, and those promises are cancelled. The money disappears, and this is incredibly important to understand. Creating a loan makes new money. Repaying a loan cancels that money. The slate is wiped clean. The money has gone.
And that's the case with regard to the government too. When the UK government spends, it tells the Bank of England to make payments. Its account with the Bank of England is increased; new money is created. And when tax is paid, the government accepts its own money back, and then it cancels it. That's what tax is for. Tax is a deliberately created debt to enable the government to cancel the money that it puts into circulation as a consequence of its spending. Tax does not then fund spending; money creation does.
So why do the pounds that we use have value? And why does the dollar have value? And why does the euro have value? And why do all the types of dollar we have all around the world have value, because I wasn't just referring to the US dollar when I made my comment?
The government creates pounds when it spends and then demands we use those very same pounds to pay our taxes. That creates a permanent need for pounds. We accept and exchange pounds because we all need them to pay our taxes. And bank deposits work as money because the government promises to accept the money in them to settle our tax bills.
There is no such promise for gold or for cryptocurrencies. They are assets. They are not money because there is no promise that represents a promise to pay that is stacked behind them. Only the government creates that promise and only the government can create money. Everything else is a fiction.
But let's be clear, money is not real wealth. That's one of the other common confusions people have. We talk about millionaires as if they're wealthy because they, in our imaginations, are sitting on a pile of notes or coins that comes to that sum of money. That is not true.
There are real limits to what money can do. Money cannot build a house. It cannot teach a child; it cannot grow food; it cannot care for someone. People use skills, knowledge, and real resources to do those things. They create value. That is what wealth is.
Money might help us to organise economic activity and reward those who take part in it, but more money does not automatically make us richer. Double the amount of money in every bank account in the UK tomorrow, and there would be no more houses, no more jobs, no more food on the shelves in the supermarket. There would just be double the amount of money, but real wealth would be the same.
So money is not wealth. Money is a tool we use to facilitate the exchange of wealth, and wealth is the value that we create through our own efforts.
So what is money? It's a record of promises about who owes what and to whom. Those promises can be created and cancelled, but money itself is not wealth. What ultimately matters is whether we have the people, skills and resources to do what society needs, and money helps us marshal those resources so that we can create real value. Money is incredibly important, but it is not the be-all and end-all of life. It is not the be-all and end-all of the economy, and an obsession with it in any form of life is misplaced, and that includes in economics.
That's what I think. What do you think? There is a poll down below, and I will be very interested in your opinions. Please do also leave your comments, and do look at the playlist that we have put below this video because that explains how you can see more videos in this Understanding Economics series. And if you want more explanations about money, there are more on my Funding The Future blog, including a ‘View On' article which we will link to, which explains money in more depth. It's a 5,000-word essay. It expands on the themes here, and I hope that will be of use.
Poll
Thanks for reading this post.
You can share this post on social media of your choice by clicking these icons:
There are links to this blog's glossary in the above post that explain technical terms used in it. Follow them for more explanations.
You can subscribe to this blog's daily email here.
And if you would like to support this blog you can, here:
 Buy me a coffee!


Dear Richard,
Once more a great explaination as overview. It’s important for us a your community to reinforce our understanding if this abstract matter.
And it’s important to convince people that money is and always was abstract, despite representations by shells, tally sticks, bars of gold or coins and notes.
But it’s OK like this if we have a strong government and if our money is accepted by our neighbourg nations or even the world.
Ofc, many countries are not that much currency sovereign and they need solution to enhance this sovereignty.
But at least the strong nations must wake up and finally make good use of the abilities of our fiat system – with some non-neoliberal policies, at least!
I try to spread your views in our German Green party via workgroups on all levels which serve as a think tank structure.
I only hope many will watch your videos directly. And I hope to find some published references to support your views as truth not as opinion.
In the end, some people want papers to read nit only great videos.
Keep up explaining so well!
Cheers form a great fan of your work, from Germany, Sachsen-Anhalt (hopefully wi no AfD bullshit politics coming)
Ricco Lindner
Have a good day in Ely folks!
A thought… one exception to the rule that you have to pay UK taxes in sterling. The government occasionally accepts stately homes being given to the charitable National Trust, in lieu of inheritance tax, and as long as the NT also can raise money to care for the property, then the tax debt is settled, the numbers on the ledgers change, the NT has the property, and no “money” reaches the Treasury. If you look at the size of the NT land and property portfolio, that’s a lot of inheritance tax that never reached the Treasury although proportionately, its not a big percentage of the annual IHT take.
Its beyond my limited understanding of economics, but somewhere, in there, is an argument that supports your explanation about money (and gives our family a nice portfolio of land and property to enjoy visiting).
But the point is, the settlement is valued in pounds. Payment is made in pounds, without a sale of the asset being required.
What exactly is the point in emphasising that the money has value because of its use in settlement with the government? This seems somewhat pedantic, when people will only engage with the system if they are forced, or agree with it. If the government has to coercively force you to accept their money in exchange for the things they ‘spend’ on, regardless of whether you want to, there isn’t an obvious value interpretation. No choice was made, no comparison is available, and the ‘money’ is effectively orthogonal to the economy overall, so most economic activity effectively occurs in the ‘underground’ economy in that it isn’t measured by the money, which seems fairly consistent with less credible, dollarised economies. If the money wants to be used to measure incomes for proportional taxes rather than arbitrary lump sums completely disconnected from the economy, then it has to be aligned with the preexisting basis of value, which only is meaningful if it is actually exchanged for those things. If people voluntarily engage with the money system, because the credibility of the government and ability to restrict issuance of a specific asset provides some convenience in transacting along an efficient arbitrage path between what we have (now or in future), and what we want, the money provides a derivative of the underlying exchange basis and its value comes not from just the tax mandate, but from the convenience and alignment with the economy as a whole. The ideas of government spending and taxation creating and destroying the money asset certainly seem descriptive, but why is it so important that we care about this specific taxation/spending cycle as necessary, when the money is only a numeraire (and settlement in the money can only be valued) when government and society coordinate, not just government unilaterally?
I think you are making this considerably more complicated than it needs to be. Taxation does not uniquely determine the purchasing power of money, and I have never suggested that it does. It does, however, create a demand for the currency because obligations to the state must be settled in it, and that is the foundation of the demand, which in itself is valuable and a public good.m
But that is different from asking what determines the currency’s purchasing power, or why people voluntarily use it in private exchange. Those depend upon the productive economy, institutions, confidence and widespread social acceptance as well. My argument is all those are upon the public good of government created money.
But none of that alters the point I am making: government spending creates money and taxation cancels it. That matters because it tells us that tax is not the source of the money government spends. Everything else in your comment is largely a different discussion.
Hi Richard,
Thank you for the response and that is fair, I just wonder why this point is important when it somewhat serves to degeneralise the theory? It is hard to see how MMT is any less true if we simply omit that one requirement that tax is foundational to value and the state spends first. Everything about the promise etc. feels totally viable without fundamentally requiring a government to issue or even necessarily to tax in the money, this just seems to be a convenient way we have set up these systems in the modern day, with government payments and tax liabilities as strong motivators but not necessary or sufficient in determining what money is.
I think you are progressively moving from an argument about how money actually works into a thought experiment about how money might conceivably work. I am only interested in the former. It is all that is relevant.
We have governments. They issue currencies. They impose taxes in those currencies. They spend using those currencies. None of that is remotely likely to disappear. I am interested in explaining how that system actually works so that we can manage it better.
Of course it is possible to imagine money without government, government without taxation in its own currency, or entirely different systems of exchange. But so what? We can imagine any number of monetary systems. That does not help us understand the one in which we actually live, and with which we will live.
The point of saying that government spends before it taxes is intensely practical. It exposes the false claim that government must obtain taxpayers’ money before it can spend. The point about taxation creating demand for the currency is similarly practical: it explains one of the fundamental relationships between the state, its currency and those who use it.
These things matter because misunderstanding them has enormous consequences for real economic policy. The supposed need to “find the money” is used to constrain public spending, investment and the provision of essential services. Understanding what actually happens exposes that claim for what it is.
I am interested in changing what governments do with the monetary system we have. I am not particularly interested in designing imaginary monetary systems for societies that do not exist. If you are, please go and waste your time elsewhere.
Could you please also consider one video to explain in which ways the money flows from exports and important affect the available or even created money amount in a country?
Steve Keen explains that e.g net exporting countries like Germany obtain net money flows from abroad that adds to the sectoral balance.
I just can’t understand if he means that this actually creates new money, especially if currency changes are involved when countries pay for our exports in their own currency or in foreign USD, but not in EUR (or Pounds for UK). Is money then created is someone changes USD to EUR/GBP to by goods from Gemrany/UK?
And if foreign importers pay with EUR, the surely must have obtain or “bought” them beforehand. So it’s just a flow back of earlier created money?
There are several different things being confused here.
Suppose a German company sells €1 million of machinery to an American company. Ultimately, the German exporter wants €1 million credited to its bank account. If the American buyer starts with dollars, somebody has to exchange dollars for euros. But that foreign exchange transaction does not, by itself, create euros. The dollars change ownership, and the euros change ownership.
The same is true for the UK. If an American buys British goods and pays in sterling, they either already own sterling or acquire it from somebody who does. The pounds remain within the sterling banking system; they simply change ownership.
This is also why I dislike the suggestion that money somehow “leaves the country” when we import. If I buy an American product with pounds, the pounds do not leave the sterling monetary system. The American recipient can hold them or exchange them for dollars, but if they exchange them, somebody else acquires the pounds.
What Steve Keen is describing through sectoral balances is a different issue. If Germany exports more than it imports, its domestic economy receives more financial claims from the foreign sector than it gives up through imports. The foreign sector necessarily has the opposite balance.
That is a net financial flow between sectors, but it does not follow that the foreign exchange transaction itself created new euros.
New bank money can, though, be created to finance international trade. If a bank lends an importer the money to make a purchase, that lending creates new bank money in the usual way. But it’s the bank loan that creates the money, not the export, import or currency conversion.
So there are two questions: where did the money come from, and where did it subsequently flow? They are not nthe same.
Thank you so much for clarification!!
It is what I understood from your videos. And it seems I misunderstood Steve Keen ab bit.
So it’s really just a matter if new money is created through a loan to pay for imports or if money is used, via exchange, that was already created.
And apart from that its net for of money that matters for sectoral balance.
I the just wondered: if my country (Germany) ist “export champian” for years, where does all the net Euros come from spilled in by net exporting over the years?
At some point foreign buyers must ask for EUR loans? Or are ther always enough EUR available for change, since trade of goods and service ist rather small compared to the finance sector?
The euros do not have to be created simply because Germany exports something.
If an American buys a German machine, for example, and starts with dollars, those dollars can be exchanged for euros. Someone else gives up the euros and receives the dollars. The foreign exchange transaction changes who owns the euros; it does not itself create any.
New euros might be created if a bank makes a loan to finance the purchase, but that is a separate transaction. The bank loan creates the money, not the international trade.
Germany’s persistent trade surplus means, in accounting terms, that foreigners are acquiring German goods and services whilst Germany is accumulating corresponding financial claims on the rest of the world. That is the important macroeconomic consequence.
And yes, the enormous scale and liquidity of modern financial markets means there is normally no need for each foreign purchaser of German goods to go looking for a new euro loan. Existing euros are continually being exchanged between their holders.
And what happens if there is a trade imbalance? Eventually, exchange rates shift a little. As MMT suggests, of course. The emphasis is usually on a little. Look at histoty.
Thanks to all for this much needed analysis of the realities of money.
Might the dangers of money also be relevant?
Might Neoliberalism prioritise money over real resources through its externalisation/deliberate ignoring of real resources and its obsessive target of short term profit ahead of long term human well-being?
When someone repays a bank loan, they also have to pay interest. They have indeed promised to pay this, extra to the amount of the loan. Where does this computer entry come from? It cancels the interest one promised to pay, but wasn’t part of the loan. What is the opposing entry in book-keeping? Is this even more abstract than money, or on the same level? It doesn’t seem as if this interest gets anything in the real world, as an ordinary loan can do. I’m sorry if the answer to this is just obvious.
That is a good question, often asked.
Suppose the bank lends you £100 and charges £5 interest. The bank creates the £100 principal when it makes the loan, but it does not create an additional £5 for the interest.
When you repay the £100 principal, your deposit falls by £100 and the bank’s loan asset falls by £100. That £100 of bank-created money is cancelled.
The interest is accounted for differently. When you pay the £5 interest, your deposit falls by £5, but the bank records £5 of interest income. The money is therefore transferred to the bank rather than cancelled as repayment of principal is.
That income then contributes to the bank paying its staff, suppliers, depositors, taxes and dividends, amongst other things, so much of it subsequently returns to circulation.
There is therefore nothing more abstract about interest. It is simply a transfer of already existing money from the borrower to the bank in payment for the service the bank has provided and the risks and costs it has assumed. The crucial distinction is that principal repayment cancels bank-created money; interest payment transfers existing money. It does not result in new money creation. It diverts income instead.
Thank you
What I concluded from this issue is, that because interest alone (and because may not get into negative equity) we could not run on private debt by private banks alone, since interest payments (and similar transfers) require extra income which could not be provided by the private banks alone but by governement spending.
Such state money would come into the national pool e.g. by payments of rents, any type of government benefits, government payments for services etc.
Is this a correct view, or rather not?
It’s wrong. Interest is just another purchase of money created for other reasons. Do not create something special out of it for that reason.
An interesting post and infographic which has got me thinking about money and cryptocurrencies. I suspect that recent large donations to certain political parties are about deregulating digital assets, so that crypto business can obtain British bank accounts and that UK customers have no restrictions on transfers to crypto firms. The crypto industry probably wants full FCA authorisation to make generic “crypto” de-risking harder to defend. The British banking ecosystem has a reasonable counter-argument that authorisation does not relieve the crypto industry of its own legal and commercial responsibility for financial crime risk. Ultimately free market pressure groups like cryptocurrencies and decentralised tech as a way to challenge what they see as the overreach of the Bank of England. Perhaps their end game is the “denationalisation of money”…
I am inclined to agree
I like the new info graf8c about money! However, I always felt that point 7 needs to be somewhat extended. Because beyond the basic issue of needing currency to pay taxes, I believe you also need a great enough acceptence, at least domestically but also abroad. This issue divides currency-souvereigj from less sovereign countries. The latter still have the opportunity to pay for everything domestically with their own money. But what if everyone immediately trades all their local currency to lets say USD for daily business and trade it just back before paying taxes – enough USD available, provided?
Why do you make up ridiculous hypotheses to waste my time with?
Look out of your window. Is the dollar / pound / euro accepted? Why do you think so? Why not ask that, rather than wonder why it might not be when that has not happened?